If you are wondering how to handle a letter from the IRS, the answer is simpler than most people expect. Read it, confirm it is genuine, find the notice number in the top right corner, and reply before the date printed on the page. The whole process usually takes 20 to 40 minutes once you have your tax records nearby.
Most IRS mail is routine. A large share of it is an automated notice about a mismatch between what you filed and what IRS records show, and a plain reply form in the envelope settles it. The letters that need real attention are the ones about money you owe, a return under examination, or a refund the IRS is holding.
Nothing on a tax notice means an audit by itself, and nothing means arrest. Take a breath, put the envelope on the table, and work through the steps below. This is general information about IRS procedure, not individualized tax advice, so check anything case-specific with the IRS or a qualified tax professional before you act.
Last updated: October 2026
Table of Contents
- What You Need
- Step-by-Step
- 1. Read the notice and identify the IRS form or topic
- 2. Confirm that the letter is genuine
- 3. Check whether the notice is about a filing error, balance, or missing information
- 4. Gather the records needed to respond
- 5. Choose the official response method
- 6. Respond before the stated deadline
- 7. Follow up and keep records
- What most readers ask about timelines
- When to stop doing it yourself
- Common Mistakes
- Frequently Asked Questions
- How can I tell if a letter from the IRS is real?
- What should I do if I receive an IRS letter and cannot pay?
- How long do I have to respond to an IRS notice?
- Should I call the phone number printed on the letter?
- When should I contact a tax professional instead of handling the notice myself?
- Conclusion
What You Need
Six things make the rest of this much faster. Most people already own five of them and just need to gather them in one place instead of hunting through drawers.
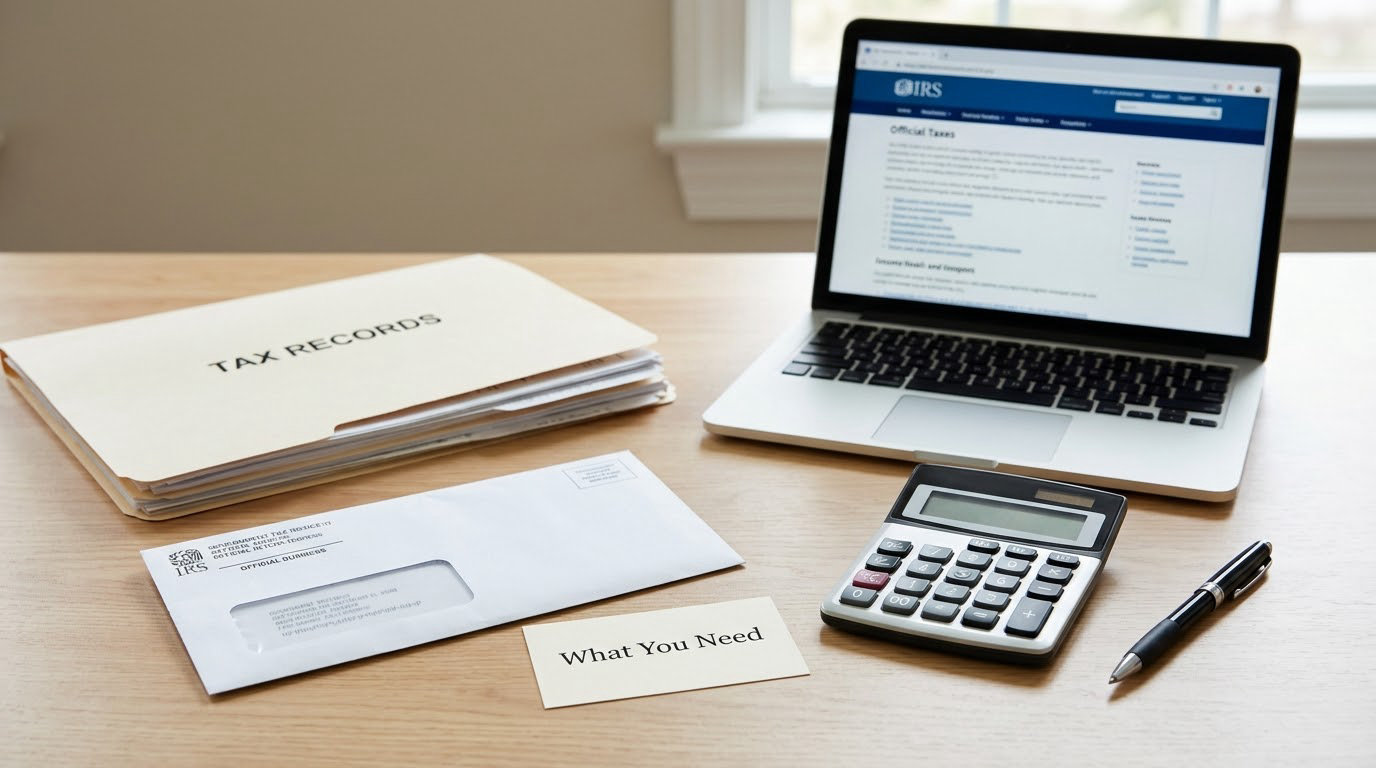
- The notice itself. Keep the envelope, because the IRS uses the barcode number on it to match your account.
- Your tax records for the year named on the notice: the return you filed, the filed copy of your Form 1040, and any payment confirmations.
- Identity information: your Social Security number or Individual Taxpayer Identification Number, filing status, date of birth, and the exact address on the return.
- A worksheet or calculator, because you will need to add up figures from several documents.
- Access to irs.gov in a browser. Not a phone number from the letter, and not a link in an email.
- The response deadline, which you write on the top of your worksheet the moment you see it.
A paper calendar helps more than it sounds. Deadlines are the single most common reason a small problem turns into an expensive one, and they are easy to lose track of when they sit on a page you file away.
Step-by-Step
1. Read the notice and identify the IRS form or topic
Every IRS letter names itself in two places, and both matter. The notice number sits in the top right corner, in a format like CP2000 or LT11. The page number and the form title, such as Form 4506 or Letter 5071C, tell you which document IRS expects back from you.
The topic line near the top will usually say what the letter is about in plain language: your refund, a proposed adjustment to your return, a balance due, an identity check, or an examined return. Read that sentence before anything else. It is the reason the letter exists.
Write two things down: the notice number and the date printed near the top or bottom as the deadline. The deadline matters because most IRS notices start a clock the moment the notice is dated, not the moment you open it. Interest and penalties keep accruing while a balance sits unpaid, which is the mechanical reason the IRS pushes so hard for a fast reply.
2. Confirm that the letter is genuine
Genuine IRS letters arrive by mail, and genuine IRS phone calls almost never arrive out of the blue demanding an immediate payment. IRS.gov publishes the rule plainly: the agency will never call, text, or email asking for a payment by gift card, wire transfer, or payment app. If your letter pushes you toward any of those, stop reading it as a tax notice and read it as a scam.
Four checks catch almost every fake. First, look for the notice number and the IRS letterhead with a valid internal office address. Second, check the payment instructions: an official notice routes payment through Direct Pay, a check payable to the United States Treasury, or an IRS.gov payment page. Third, open irs.gov yourself by typing the address, never by tapping a link in the letter, and search the notice number to confirm it matches. Fourth, compare the phone number printed on the page against the one listed on IRS.gov before you dial anything.
People on tax forums repeat this constantly. Readers have been burned by letters that carry a completely real notice number and a completely fake payment address, which is why the official-site habit matters more than reading the letter carefully.
3. Check whether the notice is about a filing error, balance, or missing information
Different situations call for different responses, so sorting the letter into a category first saves a lot of wasted effort. Here are the common ones.
A math correction or missing form. The IRS recomputed something, or a schedule never arrived. These notices usually have a response form attached. Fill it in, sign it, and send it back.
A proposed adjustment. IRS disagrees with how you reported something, such as the value of a vehicle or a deduction amount. This is the point where a reply can change the number, because they have not finalized it yet.
A refund delay or an offset. Your refund is on hold, or part of it was applied to an old balance or past-due child support. An offset notice tells you which debt took the money. Disputes about child support offsets usually belong with the agency that ordered the offset, not the IRS.
An identity verification request. Letter 5071C and similar letters ask you to confirm your identity online, by phone, or by mail within a set window. These carry real deadlines and are heavily imitated by scammers.
A collection notice. The CP90 and CP504 series means the IRS has already determined you owe a balance and has moved into collection. These carry the shortest clocks and the most serious consequences if ignored.
Something addressed to a deceased person’s Social Security number. CP01H and CP02H notices show up in families all the time and are almost always a reporting error. The response is to report the death to the IRS, not to pay the balance.
4. Gather the records needed to respond
Pull everything that touches the tax year named on the notice before you write a single sentence. That usually means your filed return copy, the Form 1040 schedules the letter refers to, the W-2 or Form 1099 in question, your payment confirmation, and any earlier IRS letters about the same year.
Request your IRS account transcript while you are at it. IRS.gov offers an account transcript that shows what the IRS believes you owe, what it has applied, and the notices it has issued, organized by date. That transcript usually explains what triggered the letter, which is the piece readers most often never find.
Gathering records is not a reason to let the clock run. If the deadline is close, send a short response that keeps the matter alive and follow up with the full documentation. Silence is the one response the IRS treats as agreement.
5. Choose the official response method
Match the channel to the notice. A mail response form printed on the page is meant to go back by mail, and IRS guidance is explicit that the notice pages themselves should be included rather than a cover letter without them. Experienced forum contributors warn that mailing your own packet without the notice pages is a common way to have a reply discarded.
The phone works for identity verification, for asking for a notice hold while you assemble paperwork, and for questions that do not need a written record. Posting a return transcript order by mail is a separate process. Paying is done through Direct Pay, a check, or an IRS.gov payment page, never through a number in a letter. And for anything involving a return under examination, a joint return, or a deceased filer, a qualified professional is worth the cost.
One tactic that comes up constantly is asking the IRS to place a notice hold while you prepare. On notices such as CP2000, a hold on the account buys processing time so your paperwork can arrive without racing the deadline.
6. Respond before the stated deadline
A good response is short. Attach the notice pages, fill in every field the form asks for, sign and date it, add your identifying information exactly as the form instructs, and mail it to the address on the notice page rather than to a general IRS address. Keep a copy of everything before it goes.
If a payment is required, make it the same way you verified the letter was legitimate. Note the confirmation number and the date, because you will need both if the next letter says something different. If you cannot pay in full, say so in your response rather than staying silent. The IRS has options for taxpayers who cannot pay, and the conversation starts with contact.
Do not reflexively file an amended return. The same advice appears over and over in tax forums: check what the notice is actually asking for first, because a Form 1040-X sent on its own rarely answers a notice that wants a specific form or a specific figure.
7. Follow up and keep records
File the original notice with everything else from that tax year. Save your response copy, the payment confirmation, and the date you sent it. Keep a small log of who you spoke to and when, including the date and time of any phone call, since hold times are long and repeat calls cost you time you may not have.
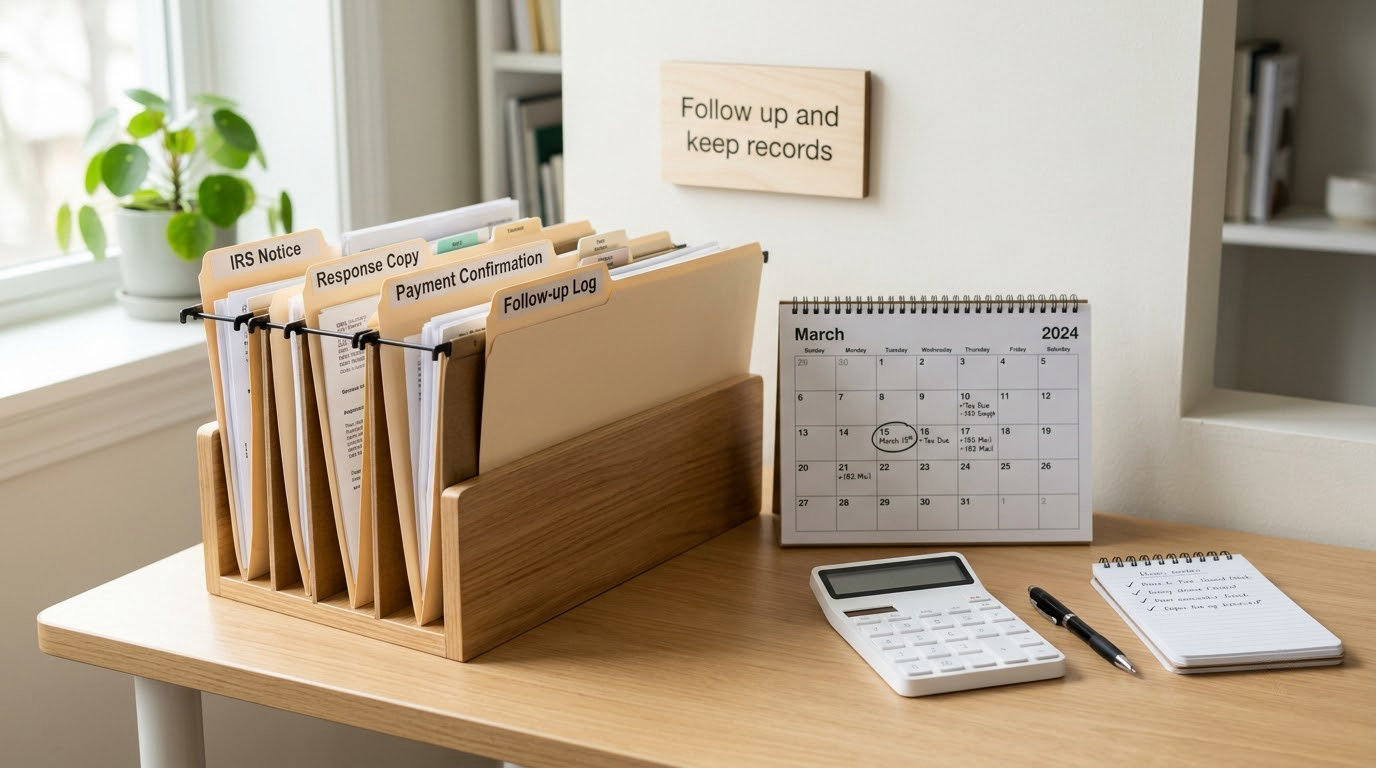
Set a follow-up date on the calendar for three to four weeks out. Mail takes time to arrive internally before anyone reviews it, and most readers who feel stuck are simply waiting in a queue with no acknowledgement in between.
If the response produces a notice you believe is wrong, escalate through the IRS’s own process. Form 9423 is the appeal that suspends collection activity while the dispute is reviewed. Your account transcript, the return copy, and any payment records form the evidence base for that appeal. Persistent unresolved problems are what the Taxpayer Advocate Service exists to handle.
What most readers ask about timelines
Expect weeks before IRS mail is even opened internally and months before a substantive answer, with no acknowledgement in between. Timelines vary by notice type and by workload, so treat any specific promise of a date as unreliable, including one from a phone agent. What you control is the response date on the notice, and that one is fixed.
When to stop doing it yourself
Hand the notice to a CPA, an enrolled agent, or a tax attorney when it involves an examination, a proposed adjustment you intend to contest, a lien or levy, a joint return where you are unsure who must respond, a deceased filer, or a balance you genuinely cannot pay. Those are the situations where the cost of a wrong move is larger than the cost of professional help.
Common Mistakes
Six errors cause nearly all of the damage, and each one has a straightforward correction.
Ignoring the letter. Nothing happens for a while, then everything happens at once, ending in a final notice. Fix: treat the printed deadline as the date it is, and respond before it even if the response is only to request more time.
Calling a number printed on an unverified letter. The number may belong to someone else entirely. Fix: open irs.gov yourself, find the number listed there, and use that one. The published line for individual assistance is 800-829-1040.
Paying through a link, gift card, wire, or payment app. IRS.gov states the agency does not accept payment that way. Fix: Direct Pay, a Treasury check, or the official IRS.gov payment page.
Filing an amended return before reading the notice. A 1040-X rarely answers a question the notice is asking. Fix: complete the form that came with the letter, and file an amended return only when that is the actual request.
Mailing your own packet without the notice pages. IRS processors match responses to the notice, and the reply can be discarded. Fix: print the notice, complete its response form, sign it, and include both.
Throwing the paperwork away. You will need the notice number and the response copy to prove what you filed and when. Fix: keep one folder per tax year, with everything in it.
One more worth naming: acting on an unexpected refund notice without checking your account transcript first. Phantom credits and incorrect refund amounts cause real panic, and the transcript is how you find out whether the money was yours before anyone spends it.
Frequently Asked Questions
How can I tell if a letter from the IRS is real?
Check four things. Look for the notice number in the top right corner and IRS letterhead with a valid office address. Confirm the payment instructions point to Direct Pay, a Treasury check, or an IRS.gov payment page. Open irs.gov by typing the address yourself and search the notice number to see if it matches a real notice. Finally, compare any phone number on the letter with the one published on IRS.gov before calling it.
What should I do if I receive an IRS letter and cannot pay?
Respond before the deadline anyway, and say plainly in your response that you cannot pay in full right now. The IRS offers installment agreements, and other options such as a temporary delay of collection may apply to your situation. Ignoring the letter is the only response that makes the balance worse, because interest and penalties keep accruing and the account escalates toward collection action.
How long do I have to respond to an IRS notice?
The deadline printed on the notice controls, and it differs by notice type. Identity verification letters usually allow roughly 30 to 60 days, many collection notices allow 30 days, and examination responses often have their own schedule stated on the page. Because the clock generally starts when the notice is dated rather than when you receive it, respond early rather than assuming you have the full window after opening it.
Should I call the phone number printed on the letter?
Only after you verify it independently. Type irs.gov into your browser yourself, open the contact page there, and compare the number listed on it with the one on your letter. If they match, calling is reasonable for questions about your account. If they differ, do not call the number on the letter at all, and treat the document as a probable scam attempt rather than a tax notice.
When should I contact a tax professional instead of handling the notice myself?
Get help when the letter concerns an examination, a proposed adjustment you plan to contest, a lien or levy, a joint return with unclear obligations, a deceased filer, or a balance you truly cannot pay. A CPA, enrolled agent, or tax attorney can file the right form, such as Form 9423 to appeal, and represent you. The cost of professional help is usually far below the cost of a collection action you could have stopped.
Conclusion
Start by confirming the sender, then read the notice number and the deadline printed on the page. Gather the return and payment records for that tax year, reply through an official IRS channel using the form that came with the letter, and keep a copy of everything you send. When the situation involves an examination, a contested assessment, or a balance you cannot pay, a qualified tax professional is the sensible next call.
Procedures, deadlines, and notice details change from year to year, so treat irs.gov as the source of record for 2026 and verify anything time-sensitive before you act on it.