Tax brackets are ranges of taxable income taxed at set rates, and the rate in your top bracket applies only to the slice of income inside that range, not to everything you earn. Understanding how tax brackets really work takes about five minutes and saves a lot of guessing later, because the marginal rate on your next dollar is not the same thing as the average rate on your paycheck.
This guide covers the U.S. federal income tax only. Rates, thresholds and definitions differ by country, change year to year, and vary by state, so treat the figures below as illustrations of the mechanics rather than a rate table to file with. I use the IRS and the Tax Policy Center as the primary sources and the Tax Foundation for context, and I flag where the simple arithmetic stops being simple.
Everything I describe here is general information, not individual tax advice. For your own return, a CPA or enrolled agent is the right call, particularly if you have self-employment income, investment gains or anything unusual.
Table of Contents
- What Are Tax Brackets, and Why Do They Exist?
- What Income Gets Placed Inside a Tax Bracket?
- Are U.S. Federal Tax Brackets Progressive?
- How Tax Brackets Really Work in a Worked Example
- Does a Higher Bracket Mean Your Whole Income Is Taxed at That Rate?
- How Do Deductions and Credits Change the Result?
- How Does Tax Withholding Relate to Your Bracket?
- What Common Tax Misconceptions Cause Confusion?
- Frequently Asked Questions
- What income is subject to U.S. federal income tax?
- What is the difference between a marginal tax rate and an effective tax rate?
- Why might my tax bracket change even though my salary stayed the same?
- Are Social Security and Medicare taxes part of my income tax brackets?
- Do state and local taxes use the same brackets as the federal system?
- Where can a taxpayer find the instructions and rates that apply to a particular tax year?
- Conclusion: What to Check First
What Are Tax Brackets, and Why Do They Exist?
A tax bracket is a range of income with a fixed tax rate attached to it. The U.S. federal system has seven of them: 10%, 12%, 22%, 24%, 32%, 35% and 37%.
The system is progressive, which means the rate rises as income rises. The policy argument for that is straightforward: the same 500 dollars of spending costs a household earning 20,000 a far larger share of its income than it costs a household earning 200,000, so the code asks more of the second household in proportion.
Two things get missed in casual conversation. First, the brackets are not buckets that hold your paycheck. They are slices of one number, your taxable income, stacked on top of each other. Second, thresholds move. The IRS indexes them to inflation using the Consumer Price Index, so the boundaries you read in an old article are almost certainly wrong for 2026. Always check the current year’s publication.
What Income Gets Placed Inside a Tax Bracket?
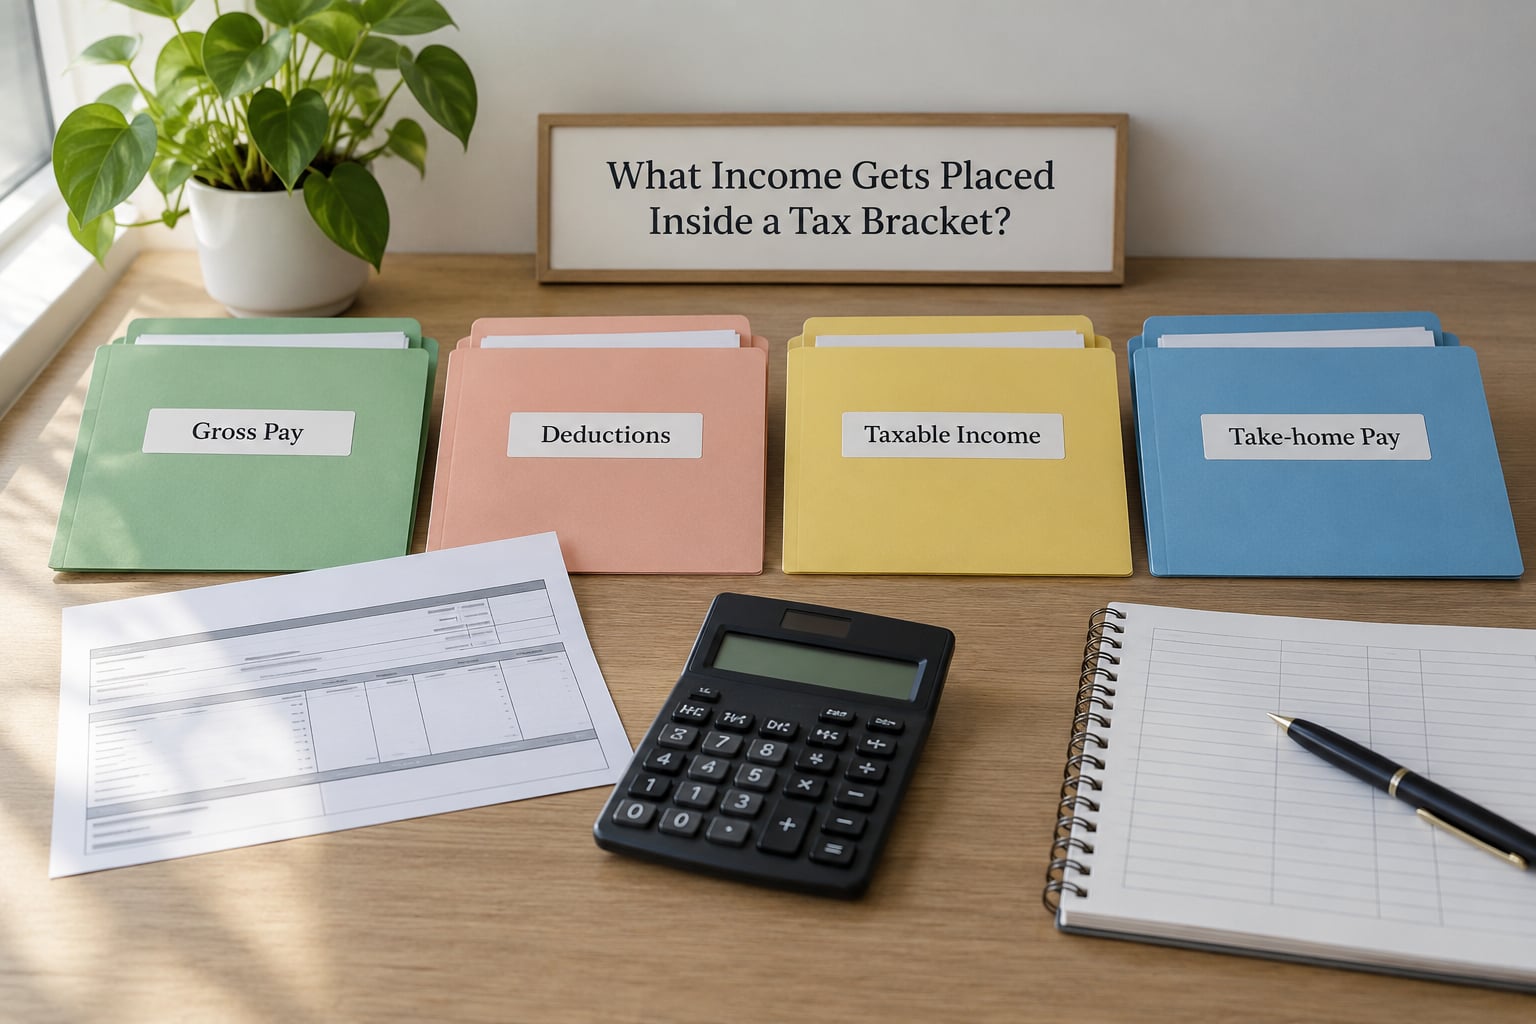
Not all your income lands in the brackets. Ordinary income does: wages, salaries, tips, most interest, and rent you collect. Capital gains and qualified dividends sit in separate, lower schedules that mirror the same brackets, so a gain can be taxed at a preferential rate rather than the ordinary rate.
The path from money in your bank account to taxable income runs through three steps:
- Gross income is everything you received before anything is subtracted.
- Adjusted gross income is gross income minus certain pre-tax deductions, including traditional retirement contributions, self-employment retirement plan contributions and some health savings account deposits.
- Taxable income is adjusted gross income minus the standard deduction or your itemized deductions, plus any taxable portion of your benefits.
So taxable income equals adjusted gross income minus your deduction. The standard deduction is a flat amount the IRS publishes each year; itemizing means listing individual deductions such as state income taxes paid, mortgage interest and charitable contributions, and using the larger figure.
The IRS then applies the tax rate schedules to that taxable income figure. The mechanics look like base tax plus a percentage of the amount over a threshold, which is exactly how the tables read: find the bracket your taxable income falls into, take the tax shown at the bottom of that bracket, then add the bracket’s rate times the amount by which your income exceeds the bracket’s starting point.
Are U.S. Federal Tax Brackets Progressive?
Yes, and the design is the whole point. Because each rate applies to only one layer, a taxpayer in the 24% bracket is not paying 24% on all of their income.
Here is the shape of the seven layers, using rounded boundaries for a single filer to illustrate the sequence. These are teaching numbers, not the published thresholds:
| Rate | Layer of taxable income (illustrative, single filer) |
|---|---|
| 10% | First 12,000 |
| 12% | 12,001 to 47,000 |
| 22% | 47,001 to 100,000 |
| 24% | 100,001 to 197,000 |
| 32% | 197,001 to 250,000 |
| 35% | 250,001 to 626,000 |
| 37% | Over 626,000 |
The IRS publishes a separate schedule for each filing status. Married filing jointly gets thresholds roughly double the single filer’s, and head of household sits between the two. That is why filing status sometimes changes your marginal rate without your income changing at all.
Two rates describe the same person and they rarely match. Your marginal tax rate is the rate of your top bracket, applied to your last layer of income. Your effective tax rate is total tax divided by total taxable income, the average you actually pay across all layers.
| Marginal tax rate | Effective tax rate | |
|---|---|---|
| What it measures | The rate on your last layer of income | The average rate across all income |
| How it is calculated | Top bracket’s rate | Total tax divided by taxable income |
| What it is good for | Deciding what an extra dollar earns you, and what a deduction saves you | Comparing your real burden across years or households |
| Typical relationship | Always equal or higher | Always equal or lower |
How Tax Brackets Really Work in a Worked Example
Take a single filer with 80,000 of taxable income. Using the illustrative layers above, the calculation runs in three passes:
| Layer | Amount in this layer | Rate | Tax |
|---|---|---|---|
| First layer | 12,000 | 10% | 1,200 |
| Second layer | 35,000 | 12% | 4,200 |
| Third layer | 33,000 | 22% | 7,260 |
| Total | 80,000 | 12,660 |
This taxpayer sits in the 22% bracket, so the marginal rate is 22%. The effective tax rate is 12,660 divided by 80,000, which is 15.8%. That gap between 22% and 15.8% is the single most useful number in this whole topic, and it is why people who see a mid-teens effective rate while sitting in the 22% bracket should not assume their return is broken.
In practice most taxpayers never run these layers by hand. Below 100,000 of taxable income the IRS publishes tax tables that give you a lookup answer directly. Above that, the IRS Tax Computation Worksheet walks through the same arithmetic I just did.
Does a Higher Bracket Mean Your Whole Income Is Taxed at That Rate?
No. Being in the 22% bracket does not mean you pay 22% on all your earnings, and this single misunderstanding drives most of the anxiety people have about taxes.
Run the wrong calculation and the right one side by side on the same 80,000:
| Method | Calculation | Result |
|---|---|---|
| Flat rate (wrong) | 80,000 times 22% | 17,600 |
| Layered (correct) | 1,200 plus 4,200 plus 7,260 | 12,660 |
The flat method overstates the bill by 4,940, which is the entire argument. Crossing a threshold taxes only what sits above it. The dollars underneath stay at their lower rate.
That is why a raise never reduces your take-home pay. If your taxable income rises from 47,000 to 52,000, the extra 5,000 is taxed at 22% and your first 47,000 is untouched, so your after-tax income still goes up, just by slightly less than the gross amount. I have seen people decline a promotion because of this myth more often than almost any other tax error, and it is worth saying plainly to anyone doing it.
The one place a “higher rate on everything” instinct is half-right is a bonus. Employers may withhold on a bonus using your top marginal rate, but the bonus is still added to your other income and taxed layer by layer at filing, not as a flat slab. If your regular income already fills a higher layer than the bonus reaches, the bonus can land at a lower effective rate than people fear.
How Do Deductions and Credits Change the Result?
Deductions and credits both lower your bill, but they operate at different points in the process and that difference matters when you are deciding whether a deduction is worth anything.
A deduction subtracts from taxable income before brackets apply. A credit subtracts from tax owed after the brackets have done their work. This is why a 1,000 deduction in the 22% bracket saves you about 220, not 1,000, and why a 1,000 credit saves you the full 1,000. Common credits include education credits, child and dependent care credits, and premium tax credits for marketplace coverage.
Deductions also create what some people call the hidden 0% bracket. Your standard deduction and your itemized deductions are never taxed at all, so the income they shelter sits in a layer with a rate of zero. On a traditional 401(k) or IRA contribution, that zero-rate layer runs through both the deduction and the investment’s later growth, which is why filling that layer first is a standard move among regular investors.
A few layers sit outside this simple model and will move your real bill. Self-employment tax applies to net earnings from self-employment and comes on top of income tax. The alternative minimum tax can push up your liability for certain high earners. State and local income taxes sit above the federal system with their own rates and deductions. And long-term capital gains and qualified dividends use preferential schedules rather than ordinary rates.
How Does Tax Withholding Relate to Your Bracket?
Withholding is an upfront payment to the government, not your final tax. Your employer takes money out of each paycheck based on what you claimed on your W-4 and what the IRS’s withholding tables say you owe. At filing, the IRS compares total withholding against your actual liability, and you either get the difference back or owe the difference.
This is the gap that confuses most people. Someone in the 24% bracket with an effective rate near 16% looks at a paycheck and sees a single number that is neither rate. That paycheck figure is a blended, roughly mid-year estimate built from your W-4 elections, not a statement of your bracket.
Withholding usually changes when something else changes: a new job with a different W-4, a marriage or divorce, a child claimed as a dependent, a second job added, a big one-time payment, or a correction to an allowance or credit election. A raise alone sometimes nudges the amount withheld because the tables look at your earnings, which is why your paycheck can shift a little after a promotion even though your marginal bracket did not change.
Freelancers and contractors do not have withholding at all. Income arrives without anything taken out, and the bill lands later as self-employment tax plus income tax, usually in quarterly payments. That timing gap, not the bracket rate itself, is what causes the classic freelance cash-flow surprise.
What Common Tax Misconceptions Cause Confusion?
Here are the errors I see repeated most often, including in threads on r/personalfinance and r/tax where the topic comes up constantly, and what is actually true:
| The claim | What is actually true |
|---|---|
| A raise pushes me into a higher bracket, so I lose money | Only the income above the threshold is taxed at the new rate. Take-home pay always rises. |
| There is a 40% bracket | There is not. The top federal ordinary rate is 37%. |
| The top 1% pay 40% of taxes | Their marginal rate is 37%, but their average burden is far lower because the top rate applies only to their top layer. |
| A bonus is taxed flat at my marginal rate | Withholding may use that rate, but the bonus is added to your other income and taxed layer by layer. |
| The rate on my paycheck is my tax rate | That figure is an upfront withholding estimate. Your effective rate comes from your final return. |
| A deduction saves me its full value | It saves you the value multiplied by your marginal rate, because it lowers income taxed at that rate. |
There is a second kind of confusion worth naming: people assume the rate schedules and calculator results they read are definitive for their situation. They usually are not. State taxes, self-employment tax, phaseouts of credits and deductions at higher incomes, and the alternative minimum tax all move the final number, which is why a clean illustration and a real return can differ. Where the arithmetic here gets complicated, a professional is worth the fee.
Frequently Asked Questions
What income is subject to U.S. federal income tax?
Ordinary income is: wages, salaries, tips, most interest, and rent you collect. Capital gains and qualified dividends are taxed at preferential rates through separate schedules that mirror the brackets, not at ordinary rates. Pre-tax contributions such as traditional 401(k) and IRA deposits reduce adjusted gross income before brackets apply, so they are never taxed in the current year. Certain benefits are partly taxable, and Social Security becomes taxable above income thresholds.
What is the difference between a marginal tax rate and an effective tax rate?
Your marginal tax rate is the rate of your highest bracket, applied only to your top layer of taxable income. It tells you what an extra dollar of income, or a deduction, is worth right now. Your effective tax rate is total tax divided by total taxable income, the average you pay across every layer. The effective rate is always equal to or lower than the marginal rate, and the gap widens as income rises.
Why might my tax bracket change even though my salary stayed the same?
Several things move taxable income without touching your wage. A bonus, a side project, a rental property, or investment income all add to the pile. Filing status changes do too: marrying, divorcing, or having a child alters which schedule applies. A traditional retirement contribution or HSA deposit lowers adjusted gross income. Capital gains realized in the year also count, which is one reason people file a return in a year they did not have a job.
Are Social Security and Medicare taxes part of my income tax brackets?
No. Social Security and Medicare are separate payroll taxes on wages, and they have their own rates, wage caps and rules that differ from the income tax brackets. Medicare has an additional surtax at higher earnings. None of these amounts is included in taxable income for bracket purposes, which is why a gross paycheck and taxable income never match. The employer and employee each pay a share of the payroll taxes.
Do state and local taxes use the same brackets as the federal system?
They may use similar structures, but they are separate systems with their own rates, thresholds, deductions and phaseouts. Some states have flat rates, a few tax wages at the top marginal rate, and several have no broad income tax at all. Local taxes usually apply only in specific cities. Because state deductions interact with the federal return, your true combined effective rate is usually higher than the federal number alone, sometimes by several points.
Where can a taxpayer find the instructions and rates that apply to a particular tax year?
Start with the IRS. The annual income tax rate schedules, the tax tables for lower incomes, the Tax Computation Worksheet for higher incomes, and the Form 1040 instructions are all published by the IRS for each tax year. The rate schedules arrive in a revenue procedure released in the autumn and are then indexed for inflation. Use the year you are filing for, not the year you are reading about, since thresholds change annually.
Conclusion: What to Check First
Tax brackets are progressive layers, not a single rate that applies to everything. Your marginal rate touches only the top slice of taxable income, while your effective rate is the average you pay across the whole stack, and that difference is normal.
If you take three things from this, make them these. First, estimate your taxable income for the year rather than your gross pay, since that is the number the brackets actually apply to. Second, identify your filing status, because it selects which schedule you are reading. Third, keep your marginal rate and your effective rate separate in your head, since one tells you what your next dollar is worth and the other tells you what you actually paid.
Then check the current year’s figures with the IRS before you commit them to memory, and bring in a professional if self-employment income, investment gains or anything unusual is involved. This guide explains how tax brackets really work; it does not replace advice about your situation.